The Financial Blind Spots That Are Quietly Draining American Expats Dry
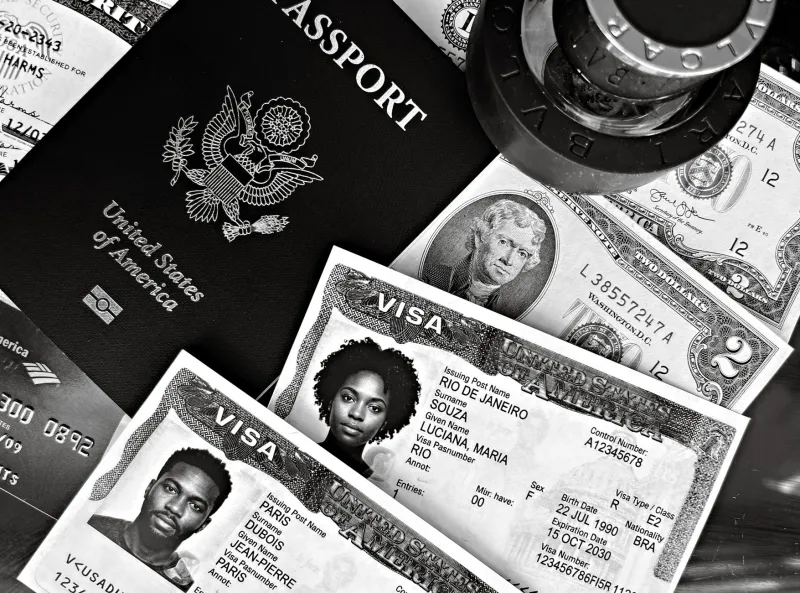
You did the math. You found a place where your dollar stretches twice as far, landed a remote job that pays in USD, and figured you'd finally get ahead financially. And for a while, it works. Then a letter shows up—or worse, a penalty notice—and suddenly that tidy little savings buffer you built starts evaporating in ways you never anticipated.
Living abroad as an American comes with a financial complexity that most expat content glosses over. Everyone talks about the Foreign Earned Income Exclusion and the general idea that you still owe the IRS. Fewer people talk about the specific, lesser-known obligations that blindside even financially savvy expats. This isn't meant to scare you out of your adventure—it's meant to keep you from learning these lessons the expensive way.
FBAR: The Reporting Requirement With Teeth
If you have more than $10,000 sitting in foreign bank accounts at any point during the year—even for a single day—you're required to file an FBAR (Foreign Bank and Financial Accounts Report) with the Financial Crimes Enforcement Network. Not the IRS. A separate agency. A separate filing. A separate deadline.
Missing it isn't a slap on the wrist situation. Non-willful violations can run $10,000 per account per year. Willful violations? Up to $100,000 or 50% of the account balance—whichever is greater. And the IRS has been increasingly aggressive about enforcement in recent years.
The kicker is that most expats don't even realize this filing exists until they're already in violation. Your regular tax preparer back home may not flag it either, especially if they don't specialize in expat returns. If you've got money sitting in a local bank account abroad—which you almost certainly do—make sure you know your FBAR obligations cold.
State Tax Residency: The Home You Thought You Left Behind
Here's one that catches people completely off guard: some U.S. states don't let you go that easily. California, New York, New Mexico, and South Carolina are notorious for maintaining what's called "domicile" or "residency" status even after you've moved abroad, unless you can prove you've definitively severed ties.
What counts as a tie? A driver's license. A storage unit. A gym membership. A bank account. Even a car registered in the state. People who assume they've left their state tax obligations behind because they're physically living in Medellín or Chiang Mai often discover they've been accruing state tax liability the entire time.
If you're from one of these states, the process of establishing non-residency requires deliberate, documented action—not just moving. Get professional advice before you go, not after you've spent two years technically still being a California taxpayer.
Currency Conversion: Death by a Thousand Fees
This one is less dramatic but relentlessly consistent. If you're getting paid in dollars and spending in a local currency, you're converting money constantly. And each conversion—whether through your bank, PayPal, Wise, or a local ATM—comes with a cost.
Most Americans don't track these fees carefully because each individual transaction seems minor. But add up a year's worth of ATM fees, unfavorable exchange rates, international wire charges, and credit card foreign transaction fees, and you're often looking at hundreds—sometimes thousands—of dollars quietly disappearing.
The fix is relatively straightforward once you know to look for it: use accounts designed for international living (Charles Schwab's checking account, for instance, reimburses all ATM fees globally), move money in larger, less frequent batches, and use a service like Wise for international transfers rather than your traditional bank. Small habits, meaningful savings.
Selling Foreign Real Estate: The Tax Event Nobody Sees Coming
Some expats, especially those who've settled in one place for a few years, eventually buy property. It feels like a smart move—building equity, investing locally, maybe generating rental income. What they often don't anticipate is what happens when they sell.
The U.S. taxes its citizens on worldwide income, including capital gains from selling foreign real estate. Depending on how long you owned the property and what the exchange rate did during that period, you could owe a significant chunk to the IRS even if the local country doesn't tax the transaction at all—or taxes it at a much lower rate.
There's also a currency gain complication that trips people up: if the local currency appreciated against the dollar while you owned the property, the IRS may treat that currency movement as an additional taxable gain, separate from the actual increase in property value. It's a scenario that genuinely surprises people who've done everything else right.
The PFIC Problem: Foreign Investments That Punish You
If you've tried to invest locally—buying into a foreign mutual fund, an ETF domiciled outside the U.S., or a similar vehicle—you may have unknowingly triggered Passive Foreign Investment Company (PFIC) rules. The U.S. tax treatment of PFICs is notoriously punishing: complex reporting requirements, punitive tax rates on gains, and interest charges that can make these investments financially worse than holding cash.
Many expats discover this after the fact, when they go to sell a foreign fund they've been contributing to for years and realize the tax bill is crushing. The general advice from expat tax specialists is to avoid non-U.S. investment funds entirely and stick to U.S.-domiciled accounts and funds wherever possible, even while living abroad.
A Quick Checklist Before Things Get Complicated
If you're already abroad or planning to go, run through these before the end of the tax year:
- FBAR threshold check: Add up all your foreign account balances. If they've collectively exceeded $10,000 at any point, you need to file.
- State residency audit: Research your home state's specific rules on domicile. If it's California, New York, or a similarly aggressive state, talk to a tax professional about formally establishing non-residency.
- Fee inventory: Review what you're actually paying in conversion fees and international banking costs. Switch to expat-friendly accounts if you haven't already.
- Foreign property review: If you own or are considering buying foreign real estate, consult a tax advisor about the full picture of U.S. tax exposure before you commit.
- Investment check: If you've bought any foreign funds or investment vehicles, find out whether they qualify as PFICs and get ahead of the reporting requirements.
- Hire the right professional: Not all CPAs understand expat tax law. Look for someone who specifically works with Americans abroad—it's a specialized area and the difference in quality of advice is significant.
You Can't Outrun the Paperwork
Living abroad is genuinely one of the most financially liberating things an American can do. Lower costs of living, geographic arbitrage on your income, experiences that money back home couldn't buy. None of that changes. But the U.S. tax system was not designed with the globally mobile citizen in mind, and the gaps in that system have a way of finding you eventually.
The good news is that most of these pitfalls are entirely avoidable with the right information and the right help. You just have to go looking for them before they come looking for you.